Structuring Seller Rollover Equity in Strategic Bolt-Ons: Post-Close Control, Pari Passu Ranking, and Waterfall Traps
A strategic guide for venture-backed acquirers and scale-up founders on preserving institutional capital structures while aligning incoming seller incentives. venture-backed acquirers and scale-up founders
Content reviewed and verified by Graham Chee, with FCPA-led practice at Local Knowledge, Mascot NSW. Continuous CPA Australia member since 1986. Prior career at Goldman Sachs, BNP Investment Management and Merrill Lynch.. Last reviewed October 2026. Next review scheduled for January 2027.
TL;DR
A strategic guide for venture-backed acquirers and scale-up founders on preserving institutional capital structures while aligning incoming seller incentives. [venture-backed acquirers and scale-up founders](https://www.ding.ventures)
Key Takeaways
- Pari Passu vs Preferred Equity Ranking: Inserting a rollover seller directly into an existing preferred share class gives them downside liquidation preferences ahead of ordinary common founders. Rollover consideration should ordinarily be issued as ordinary shares or a distinct non-voting ordinary class, ensuring pari passu ranking with existing common equity rather than institutional preference stacks.
- Scrip-for-Scrip Tax Neutrality (Subdivision 124-M ITAA 1997): Sellers want tax deferral on unrealised capital gains. To access scrip-for-scrip rollover relief, the acquiring entity must reach at least an 80 percent voting share threshold in the target company, and all original voting shareholders must be offered participation on substantially identical terms.
- Voting Thresholds and Board Reserved Matters: Diluting your cap table with an active target founder requires updating your voting pools. Thresholds for special resolutions under the Corporations Act 2001 (75 percent) and investor reserved matters should be insulated against blocker stakes created by concentrated rollover holdings.
- AASB 3 Consideration vs Post-Combination Compensation: If rollover equity or top-up earn-outs are contingent on the seller remaining employed post-close, AASB 3 mandates that this equity value be expensed through profit or loss as employee remuneration rather than treated as capitalised purchase consideration, creating substantial downward pressure on post-acquisition EBITDA.
- Leaver Mechanics and Reverse Vesting: Unvested rollover equity should be protected by rigorous bad leaver and good leaver provisions. If the acquired founder departs inside 24 to 36 months, the acquirer must maintain buyback or call-option rights at nominal value or fair market value to avoid dead equity sitting permanently on the register.
Deal-Grade Rollover Structuring
Aligning growth incentives without compromising your cap table
Seller rollover equity enables a scaling acquirer to fund strategic bolt-on acquisitions by offering equity consideration, aligning the target founder with long-term enterprise value while conserving precious cash runway. However, issuing equity to an incoming founder must be executed cleanly so it does not contaminate existing preferred return hurdles, skew corporate voting thresholds under your shareholders agreement, or inadvertently grant senior liquidation rights over your Series A or Series B investors. This analysis is written by Graham Chee, FCPA, CPA — Fellow of CPA Australia since November 2005, continuous CPA member since 1986, and principal of Local Knowledge, a principal-led practice based in Mascot NSW since 2003 rigorous business valuation methodologies. When Sydney scale-ups execute bolt-on acquisitions, navigating rollover equity requires precision under Australian corporate law and tax frameworks. Between Section 124-M scrip-for-scrip rollover relief under the Income Tax Assessment Act 1997 (ITAA 1997) and AASB 3 Business Combinations fair-value rules, the financial architecture of the transaction determines whether the deal accelerates scale or saddles your cap table with structural friction.
Key Deal Considerations
Critical legal and financial levers for high-growth ventures
Pari Passu vs Preferred Equity Ranking: Inserting a rollover seller directly into an existing preferred share class gives them downside liquidation preferences ahead of ordinary common founders. Rollover consideration should ordinarily be issued as ordinary shares or a distinct non-voting ordinary class, ensuring pari passu ranking with existing common equity rather than institutional preference stacks.
Scrip-for-Scrip Tax Neutrality (Subdivision 124-M ITAA 1997): Sellers want tax deferral on unrealised capital gains. To access scrip-for-scrip rollover relief, the acquiring entity must reach at least an 80 percent voting share threshold in the target company, and all original voting shareholders must be offered participation on substantially identical terms.
Voting Thresholds and Board Reserved Matters: Diluting your cap table with an active target founder requires updating your voting pools. Thresholds for special resolutions under the Corporations Act 2001 (75 percent) and investor reserved matters should be insulated against blocker stakes created by concentrated rollover holdings.
AASB 3 Consideration vs Post-Combination Compensation: If rollover equity or top-up earn-outs are contingent on the seller remaining employed post-close, AASB 3 mandates that this equity value be expensed through profit or loss as employee remuneration rather than treated as capitalised purchase consideration, creating substantial downward pressure on post-acquisition EBITDA.
Leaver Mechanics and Reverse Vesting: Unvested rollover equity should be protected by rigorous bad leaver and good leaver provisions. If the acquired founder departs inside 24 to 36 months, the acquirer must maintain buyback or call-option rights at nominal value or fair market value to avoid dead equity sitting permanently on the register.
Drag-Along and Tag-Along Synchronization: Bolt-on rollover holders must be bound to the parent company's shareholders agreement, guaranteeing that future liquidity events or majority institutional drag-along rights cannot be impeded by minority rollover dissenters.
Practical Application
Navigating control, valuation, and waterfalls in Sydney scale-ups
Consider a Sydney-based venture-backed scale-up generating 12 million dollars in annual recurring revenue that completes an 8 million dollar bolt-on acquisition of an unbacked competitor. Rather than funding the purchase purely with cash reserves, the founder structures the deal with 50 percent upfront cash and 50 percent rollover equity. If the acquirer issues standard Series A preferred stock to the seller, that seller immediately captures a 1x non-participating liquidation preference, jumping ahead of the original founding team upon a trade sale. The correct commercial architecture issues ordinary shares backed by a formal deed of accession to the parent shareholders agreement, establishing pari passu treatment with common stock while leaving institutional liquidation preferences intact optimising institutional capital structures. Furthermore, under Section 124-M of the ITAA 1997, the rollover must be structured so that the seller exchanges shares for identical interests in the ultimate holding company to preserve tax deferral, avoiding an immediate dry tax liability that could collapse the deal negotiations. Structuring this equity cleanly ensures that future venture capital rounds or growth-equity recapitalisations can proceed without friction from complex or fragmented class rights.
Strategic Execution Roadmap
A disciplined path to structuring rollover equity
Model the Waterfall
Simulate exit distributions at 2x, 5x, and 10x valuations to assess how rollover equity interacts with institutional 1x non-participating preferences and ordinary equity pools.
Structure Section 124-M Eligibility
Verify that scrip-for-scrip rollover relief criteria are satisfied under Subdivision 124-M, ensuring the 80 percent target voting control threshold is secured.
Execute Accession and Leaver Covenants
Integrate the incoming seller into the primary shareholders agreement with standard drag-along, tag-along, and milestone-linked leaver call-option mechanisms.
Audit Post-Close Accounting Treatment
Review share-based payment agreements under AASB 2 and AASB 3 to confirm whether consideration is treated as capital goodwill or expensed operating compensation.
Common Questions
Direct commercial answers for founders and investors
Q.Can rollover sellers receive preferred shares alongside institutional investors?
While legally possible, it is commercially inadvisable. Granting preferred shares to a seller provides them with liquidation priority and defensive vetoes intended for institutional cash investors. Rollover equity should almost always sit in common ordinary shares pari passu with the founders.
Q.How does Subdivision 124-M scrip-for-scrip rollover relief protect the seller?
Under Subdivision 124-M of the ITAA 1997, target shareholders can defer capital gains tax on the equity proportion of their sale until they ultimately sell their replacement shares in the acquiring company, provided the acquirer obtains at least 80 percent ownership.
Q.What happens if a rollover founder resigns shortly after the acquisition?
A robust shareholders agreement includes reverse vesting or leaver clauses. If the seller leaves without cause inside a defined lock-up period (commonly 24 to 36 months), the company retains an option to repurchase the unvested portion at the lesser of cost or fair market value.
Q.Why does AASB 3 classification matter for post-close performance?
Under AASB 3, if seller equity continuity is legally tied to ongoing employment rather than enterprise valuation alone, the Australian Accounting Standards Board requires the value to be booked as remuneration expense, directly reducing reported operating earnings.
About the Author
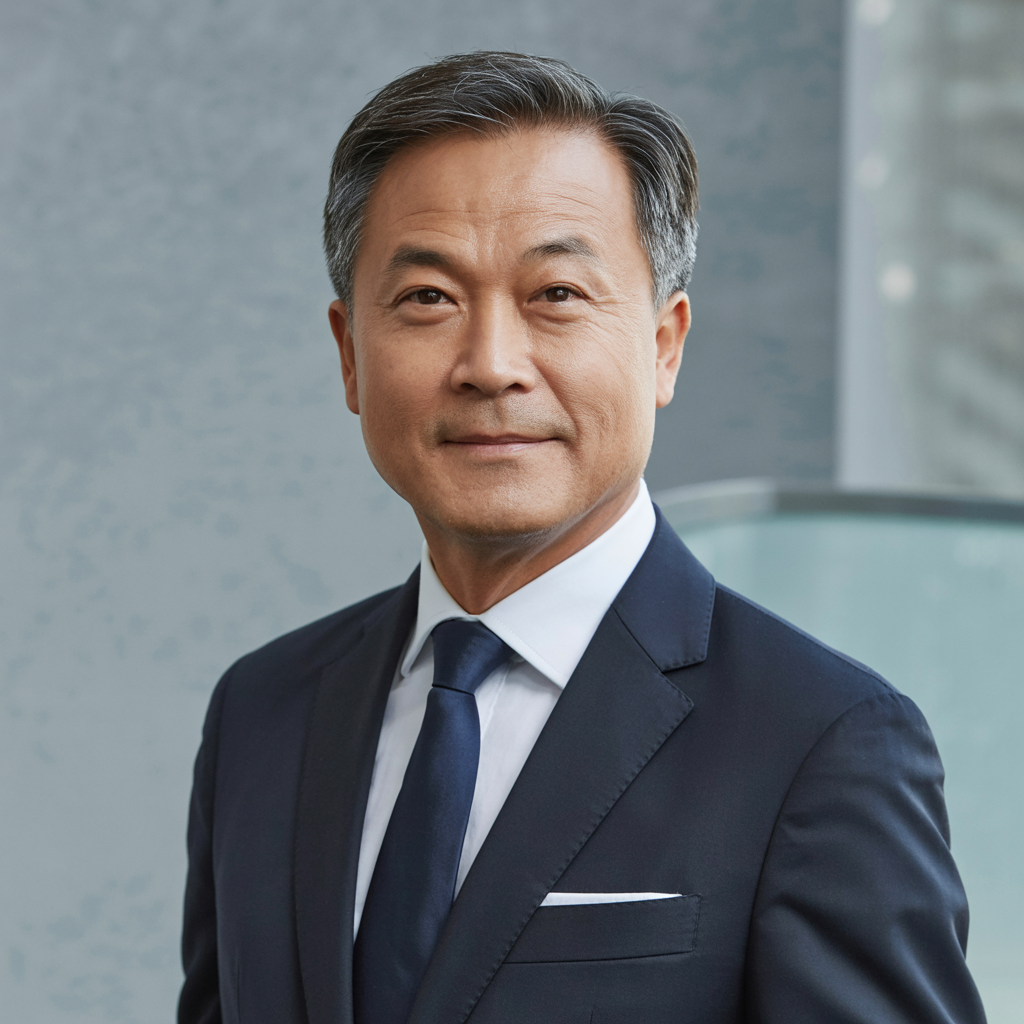
Graham Chee, FCPA, CPA, GRCP, GRCA
Principal and Founder, Local Knowledge
Graham Chee is the principal and founder of Local Knowledge, an FCPA-led Australian practice that brings institutional-grade compliance, investment-structure and intellectual-property experience directly to owner-managed businesses. Graham is a Fellow of CPA Australia (FCPA since November 2005, continuous CPA member since 1986) and holds the OCEG Governance, Risk & Compliance Professional (GRCP) and Governance, Risk & Compliance Auditor (GRCA) designations. His prior career includes senior roles at Goldman Sachs, BNP Investment Management and Merrill Lynch. Graham was previously portfolio manager of the Asian Masters Fund (IPO December 2007 – 31 December 2009), which returned +29% in AUD terms versus the MSCI Asia Pacific (ex Japan) benchmark. He signs off on 100% of client files personally.
Areas of Expertise:
Industry-specific insights
This article is especially relevant to these industries. See how we tailor our services for each.
Get Expert Guidance on M&A Equity Structuring
Local Knowledge provides principal-led strategic finance and transaction advisory. Every transaction involves distinct legal and tax considerations requiring tailored evaluation.
Graham Chee FCPA, CPA, GRCP, GRCA · Principal, Local Knowledge · Mascot NSW · CPA-signed files